
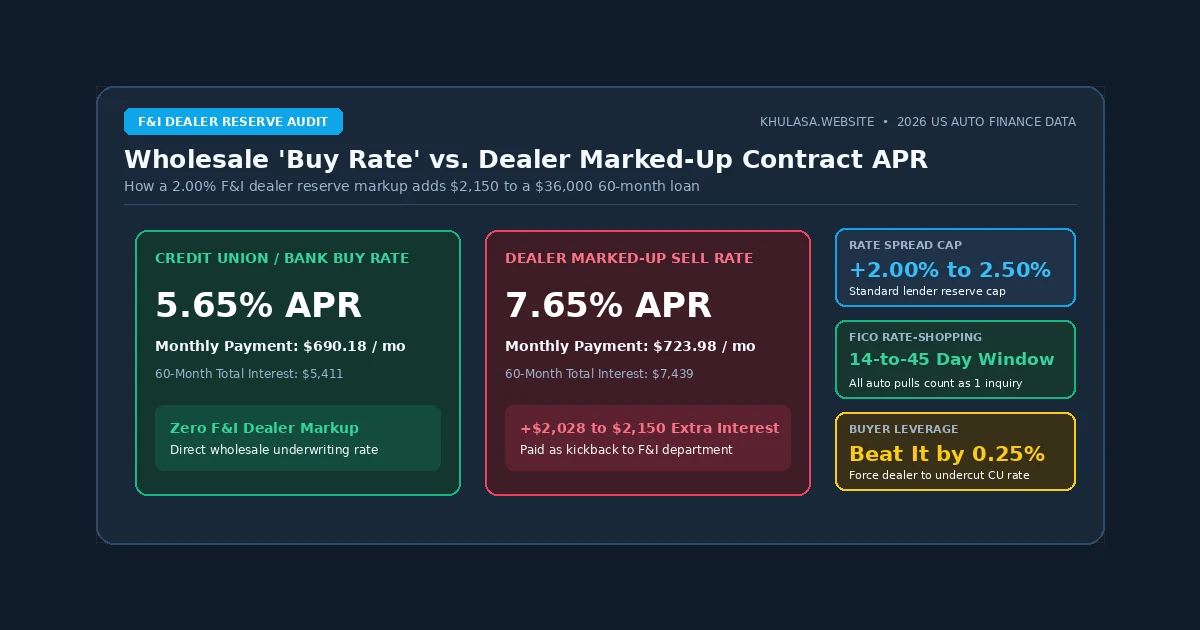
During my fourteen years of reviewing retail installment contracts, one misconception has cost car buyers more money than almost any other. Most shoppers assume that when a dealership finance manager submits their credit application to eight banks, the dealer simply hands over the lowest interest rate that pops up on the screen. Indirect auto lending does not work that way in the United States.
When a dealership's Finance & Insurance (F&I) manager transmits your credit application through RouteOne or Dealertrack, the wholesale interest rate returned by the lender is called the "Buy Rate." That is the wholesale rate at which the bank agrees to buy your contract. Under standard indirect lending agreements documented by the Consumer Financial Protection Bureau (CFPB), the lender authorizes the dealership to mark up that rate by 1.00% to 2.50% (100 to 250 basis points) into a higher retail "Sell Rate." The present value of that extra interest spread is wired directly to the dealership as a commission known as Dealer Reserve. By comparing direct credit union rates tracked by the National Credit Union Administration (NCUA) before visiting a showroom, you can cut that markup to zero.
The Dollar Cost of a 2.00% Dealer Rate Markup on a $35,000 Loan
Let's run the exact amortization math in our Car Loan Calculator to see what happens when a buyer with a 735 credit score walks into a dealership with no outside financing comparison on a $35,000 auto loan:
| Loan Term & Rate Scenario ($35,000 Principal) | Bank Wholesale "Buy Rate" | Dealer Quoted "Sell Rate" (+2.00% Markup) | Buy-Rate Monthly Payment | Marked-Up Monthly Payment | Total Extra Interest Paid by Buyer |
|---|---|---|---|---|---|
| 48-Month Auto Loan | 5.45% APR | 7.45% APR | $813.15 / mo | $845.49 / mo | +$1,552.32 |
| 60-Month Auto Loan | 5.65% APR | 7.65% APR | $670.99 / mo | $703.90 / mo | +$1,974.68 |
| 72-Month Auto Loan | 6.10% APR | 8.10% APR | $581.71 / mo | $615.35 / mo | +$2,421.72 |
| 84-Month Auto Loan | 6.65% APR | 8.65% APR | $522.30 / mo | $557.03 / mo | +$2,917.44 |
Look at the 60- and 72-month rows: because a 2.00% APR markup only raises the monthly payment by $32.91 to $33.64 per month, 90% of unrepresented buyers never notice that their interest rate was padded, and quietly hand over $1,974.68 to $2,421.72 in pure extra interest over the life of the loan.
How a Credit Union Pre-Approval Letter Flips the F&I Negotiation in Your Favor
Here is the catch for the dealership. Member-owned credit unions operate as direct lenders, meaning there is no middleman marking up your APR by two percentage points, and credit union auto loan rates average 1.25% to 2.25% lower than retail commercial bank averages according to National Credit Union Administration (NCUA) rate surveys.
Even better, getting pre-approved at your credit union 48 hours before shopping does not lock you into using the credit union, it gives you an ironclad interest-rate ceiling that forces the dealership to compete for your loan:
- Step 1, Get Your Pre-Approval Draft Before Visiting Any Dealership: Apply online with your local credit union (plus one national credit union or your primary bank) within a single afternoon. Under FICO scoring algorithms, all auto loan credit inquiries made within a 14- to 45-day rate-shopping window count as a single hard inquiry on your credit report, even if the dealership later pulls your credit as well!
- Step 2, Negotiate the Out-the-Door Vehicle Price First: Never tell the salesperson you have a credit union pre-approval check at the beginning of price negotiations. Since dealerships earn back-end profit when financing through their lenders, let them assume you are open to financing through them while you lock in the lowest Out-the-Door vehicle price in our Car Registration & Tax Calculator.
- Step 3, Present Your Pre-Approval in the F&I Office and Invite Them to Beat It: Once the Out-the-Door price is finalized in writing, place your 5.45% credit union pre-approval letter on the F&I desk and say: "I'm already pre-approved at 5.45% for 60 months with my credit union, so my payment is $667.67. If your captive lender or one of your partner banks can beat 5.25% at the exact same 60-month term with zero add-ons, I'm happy to finance through you today."
What happens next is magic: instead of marking up the bank's buy rate by 2.00%, the F&I manager will immediately drop down to the bank's flat wholesale buy rate (taking a small $150–$250 flat referral fee from the bank instead of a $2,000 rate markup) or unlock a subvented manufacturer rate at 3.9% or 4.9% APR just to capture your loan volume. You win either way, and you never pay a single basis point of dealer reserve markup.
Watch Out for the Conditional 'Spot Delivery' (Yo-Yo Financing) Trap
Walking in with a credit union pre-approval also protects you from one of the ugliest practices in retail auto sales: conditional spot delivery, widely known as "yo-yo financing." In a spot delivery, the dealership lets you drive the new car home on a Saturday evening before any bank has actually funded the loan contract, relying on a fine-print "Conditional Delivery / Bailment Agreement" buried in your paperwork stack.
Four days later, the finance manager calls with bad news. They claim the bank "rejected" your 5.9% APR contract and demand that you return to the dealership immediately to sign a new contract at 9.4% APR or pay an extra $2,000 down. When you bring your own credit union pre-approval draft, your loan underwriting is already finalized before you ever touch the steering wheel.